
Roofing Insurance Claims in Fresno: When a Claim Actually Works (and When It Won't)
By Smart Home Improvements ·
If you searched “will insurance cover my roof” or “roof insurance claim Fresno,” you have probably already gotten two very different answers: an insurance page that stays vague on purpose, and a contractor who swears they can get your whole roof paid for. We would rather just tell you the truth, because we inspect roofs across the Valley every week and we see how these claims actually play out.
Here is the honest version. Some roof claims genuinely work, and when they do, good documentation matters. Most roof claims in the Central Valley do not work, and the reason is simple once someone explains it. We are a licensed California contractor (CSLB #1129883, working here since 2014), and we will give you a straight inspection either way.
The honest truth most roofers won’t tell you
The single biggest reason a Central Valley roof needs replacing is not a storm. It is age plus relentless sun. Our summers run hot for months, and that UV and heat slowly cook a roof from the top down. Shingles dry out, lose their granules, curl at the edges, and get brittle. That is normal wear and tear, and it is exactly what a homeowners policy is not built to cover.
Insurance covers sudden, accidental events. It does not cover a roof getting old. A 22 year old, sun baked roof that has quietly reached the end of its life is a replacement you plan and budget for, not a claim you file. That is not a loophole or an insurance company being difficult. It is how every standard policy in California is written, and any contractor telling you otherwise is either confused or steering you toward trouble.
So the real question is never just “is my roof damaged.” It is “what caused the damage, and can I point to the day it happened.” That one distinction decides almost every roof claim we see.
Covered versus not covered
Here is the plain version of where the line usually falls. Your own policy is the final word, so read it, but this is the pattern we see on Fresno and Clovis roofs.
| Usually a covered peril | Usually not covered |
|---|---|
| A documented windstorm that tore or lifted shingles | Normal age and sun worn shingles |
| Hail that bruised or cracked the surface | Gradual granule loss and curling |
| A fallen tree or limb that punctured the roof | Deferred maintenance and neglect |
| Flying debris from a storm event | A poor or cheap prior installation |
| Sudden water intrusion caused by one of the above | Pre existing damage from before your policy |
The left column has a date. The right column happened slowly, over years. That is the whole idea in one picture.
When a roof insurance claim actually works
A claim has a real shot when you can tie specific damage to a specific event. The strongest cases look like this:
- A datable wind or hail event. A storm rolls through, and afterward you have shingles in the yard, lifted or torn sections, or hail bruising that was not there the week before. The date of the storm is your anchor.
- Impact damage. A tree, a large limb, or wind driven debris strikes the roof and punctures or crushes it. The cause is obvious and sudden.
- Sudden water intrusion from an event. The storm opens the roof and water gets in fast, staining a ceiling or soaking insulation. That is different from a slow leak that has been dripping quietly for two years.
When you have one of these, documentation is everything. Write down the date of the storm. Take photos as soon as it is safe, from the ground, of the roof, any debris, and any interior water damage. The clearer the record that an event on a known day caused the damage in front of you, the smoother the claim tends to go. This is the honest side of insurance work, and it is the part we are glad to help with. Our storm damage inspections exist for exactly this situation.
When a claim won’t work (and can still cost you)
A claim usually fails when the real cause is time, not an event. Gradual wear, old age, deferred maintenance, pre existing damage, and a poor prior installation are all things a policy is written to exclude. No amount of framing turns a worn out roof into a covered loss.
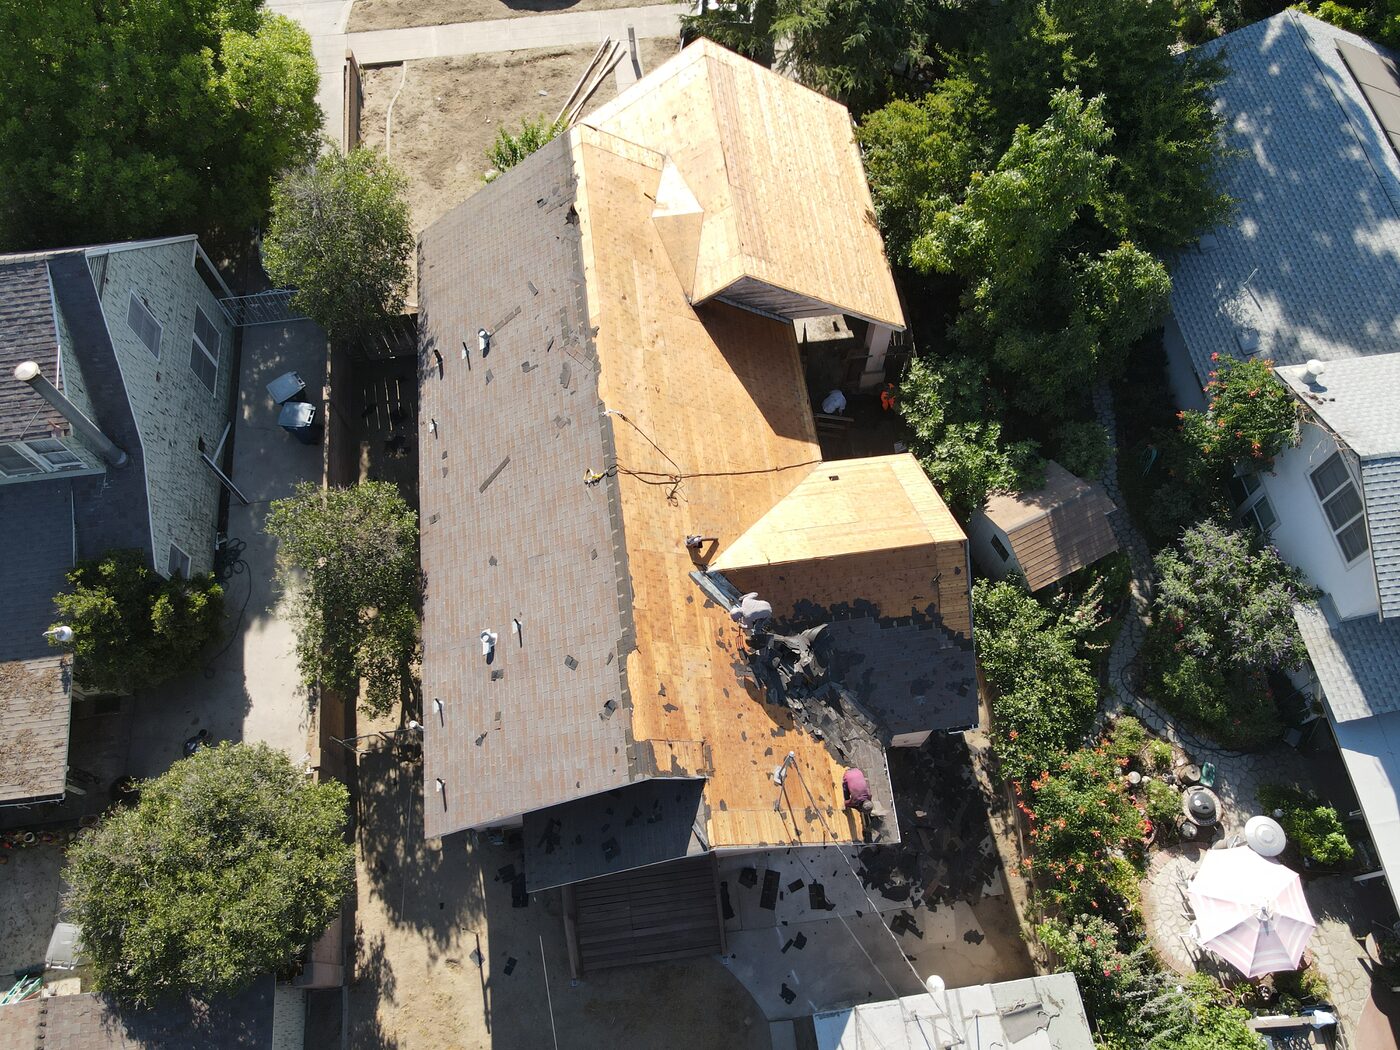
Once the old roofing comes off, the true condition shows itself. A lot of the roofs we tear off were not storm victims. They were simply done, worn thin by years of Valley sun, sometimes with old problems hidden under the surface from a cheap prior job.
Here is the part that catches people off guard: filing a doomed claim is not free. Even a claim that gets denied as wear and tear can still land on your claims history, and a record of claims can follow you when your policy renews or when you shop for coverage. So filing on a hunch, or because a salesperson pushed you to, can cost you later without ever putting a new roof on your house. That is why we do not encourage a claim unless there is a real event behind it.
How a Fresno adjuster visit actually goes
If you do file, an adjuster from your insurance company comes out to inspect. It helps to know how that visit works so nothing surprises you.
The adjuster gets on or near the roof, looks for the damage you reported, and decides whether it matches a covered event or reads as wear and tear. If they approve it, they write a scope, which is their list of what they will pay to repair or replace and what they think it costs.
Two terms decide what actually hits your bank account:
- Replacement cost value pays what it costs to replace the damaged roofing now.
- Actual cash value pays that amount minus depreciation for the age and condition of your old roof. An older roof has more depreciation, so an actual cash value settlement on a worn roof can be a lot smaller than people expect.
Which one applies is written into your policy, not decided on the day. On top of that, your deductible comes out of the payout. So an approved claim does not mean the insurance company hands you a free roof. It means they cover their share of a covered loss, after depreciation and after your deductible. Knowing that ahead of time keeps the settlement from feeling like a letdown.
The storm chaser warning
After any real storm, and sometimes after no storm at all, the door knockers show up. The pitch is always some version of “we can get your whole roof paid for by insurance, just sign here.” Watch out for that.
No honest contractor can promise you an outcome from your insurance company. And the crews that lean hardest on that promise are often the ones willing to manufacture or exaggerate damage to force a claim through. That is insurance fraud, and it is not the contractor who carries the risk. It is you, the homeowner and policyholder, whose name is on the claim.
We will not do that, and we will tell you so to your face. We document the real condition of your roof with photos and let the facts speak. If you have a legitimate event, honest documentation is what actually helps your claim. If you do not, we are not going to invent one and put you at risk to sell a job. We give you the same straight inspection either way.
What to do right now if you think you have storm damage
If a storm just came through and you are worried about the roof, here is a calm, safe order to follow:
- Stay safe first. Do not climb a wet, steep, or damaged roof, and stay clear of any downed power lines. No photo is worth a fall.
- Photograph everything from the ground. The roof, any debris or fallen limbs, shingles in the yard, and any interior water stains. Note the date of the storm while it is fresh.
- Limit further damage if you safely can. Small temporary steps to slow interior water, like catching a drip, are fine. Keep receipts for anything you spend on emergency measures.
- Do not let anyone start permanent work before the adjuster sees it. If a crew tears into the roof first, you can lose the evidence your own claim depends on. Temporary protection is one thing. Permanent repairs before the adjuster is another.
- Call a licensed contractor for an honest inspection. You want real documentation and a straight read on whether this is an event or normal wear.
Our free 21-Point Roof Inspection
The way to actually know which situation you are in is to have someone get on the roof and document it. That is what our free 21-Point Roof Inspection is for. We check shingles, flashing, penetrations, valleys, ventilation, and the condition of the roof overall, and we hand you photos with a written report of what we found.
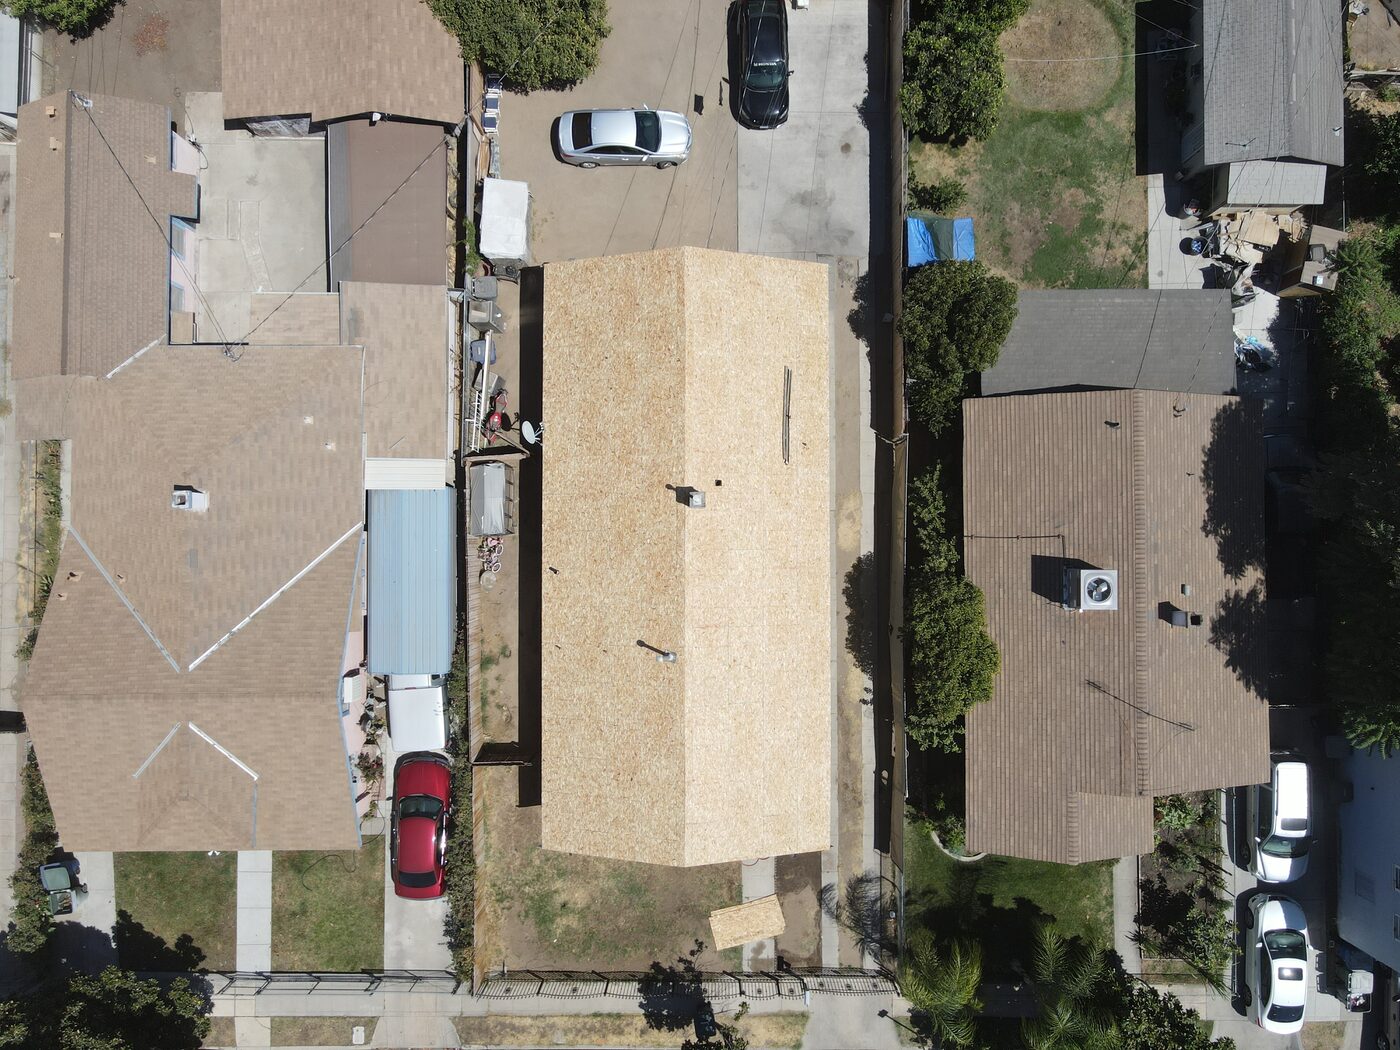
If the report shows event based damage, that photo record strengthens a legitimate claim. If it shows a roof that is simply worn out from age and sun, we tell you that plainly and give you a straight replacement estimate, no claim games attached. For most Fresno and Clovis homes a full architectural shingle reroof runs about $8,000 to $18,000 installed, and our roof replacement cost guide breaks down exactly what moves that number. If you are not sure whether you are even at replacement age yet, our post on the five signs it is time to replace your roof is a good gut check.
Either way, you end up knowing the truth about your own roof, which is more than most homeowners get from a street quote or a door knock.
Get an honest inspection
If you think a storm hit your roof, or you just want to know whether that aging roof has a claim behind it or a replacement ahead of it, we are glad to look. Book the free 21-Point Roof Inspection through our contact page, get a fast ballpark on a replacement with our instant estimate tool, or read more about our full roofing services and the questions we hear most on our FAQ page.
Call or text us at (559) 833-6945, Monday through Friday 9:00 AM to 7:00 PM and Saturday 9:00 AM to 6:00 PM. A real person answers. Smart Home Improvements is a licensed California contractor (CSLB #1129883) inspecting and replacing roofs, plus windows and insulation, across Fresno, Clovis, Madera, and the Central Valley since 2014. No obligation, no pressure, and no manufactured claims. Just an honest look at your roof.
Frequently asked questions
Will homeowners insurance cover my roof in California?
Sometimes, and it depends entirely on why the roof failed. A standard California homeowners policy covers sudden accidental events, like a documented windstorm, hail, or a tree limb through the roof. It does not cover normal wear and tear, age, or sun damage. Most Central Valley roofs that need replacing wore out from years of UV and heat, which is not a covered peril, so those are a replacement you pay for, not a claim.
Does insurance cover an old roof that is just worn out?
No. Gradual wear, old age, dried out and curling shingles, and deferred maintenance are specifically what a policy does not cover. Insurance is there for a sudden accident, not for the slow, normal aging that every roof in Fresno and Clovis goes through under our sun. A 20 plus year old roof that is simply at the end of its life is a replacement, not a claim.
What kind of roof damage does insurance actually cover?
Damage from a specific, datable event. A windstorm that tore or lifted shingles, hail that bruised the surface, a fallen tree or flying debris that punctured the roof, or sudden water intrusion caused by one of those events. The common thread is that you can point to the day it happened and show the damage the event caused.
Should I file a roof insurance claim?
Only if you have real, event based damage you can document. Filing a claim that gets denied as wear and tear still becomes part of your claims history, and a record of claims can affect your rates and coverage even when nothing gets paid. The honest first step is a real inspection so you know whether you have an event to claim or an age based replacement to plan for.
What is actual cash value versus replacement cost on a roof claim?
Replacement cost value pays what it costs to replace the damaged roofing today. Actual cash value pays that amount minus depreciation for the age and wear of the old roof, so an older roof is worth less on an actual cash value policy. Which one you have is written in your policy, and it makes a real difference in what an approved claim actually pays out. Your deductible comes out on top of that.
Can a roofer get my whole roof paid for by insurance?
Be very careful with anyone who promises that, especially a door knocker after a storm. No honest contractor can promise an outcome from your insurance company, and manufacturing or exaggerating damage to force a claim is insurance fraud that puts you, the homeowner, at risk. We document the real condition of your roof with photos and let the facts stand. If you have a legitimate event, real documentation is what helps it.
How do I prove storm damage to my roof?
Write down the date of the storm and take photos as soon as it is safe. Photograph the roof from the ground, any debris or fallen limbs, interior water stains, and anything blown off the roof into the yard. The stronger the record that a specific event caused specific damage, the cleaner the claim. Our free 21-Point Roof Inspection adds professional photos and a written report to that record.
What should I do right after a storm if I think my roof is damaged?
Stay safe first and do not climb a wet or damaged roof. Photograph everything from the ground, note the date, and make small temporary steps to limit interior water damage if you can do so safely. Do not let anyone start permanent repairs before your adjuster has seen the roof, and call a licensed contractor for an honest inspection. Keep your receipts for any emergency measures.
Do you handle roof insurance work in Fresno and Clovis?
Yes. We inspect roofs across Fresno, Clovis, and the wider Central Valley every week, and we document real condition with photos either way. If you have an event based claim, honest documentation helps it. If your roof is simply worn out, we will tell you that plainly and give you a straight replacement estimate. We are a licensed California contractor, CSLB #1129883, working here since 2014.
Get your free 21-Point Roof Inspection
A licensed local crew checks your whole roof and shows you photos of what we find. Free, no obligation.
Written by Smart Home Improvements
Licensed California contractor, CSLB #1129883, installing roofing, windows, and insulation across Fresno and the Central Valley since 2014. We do this work every week; the advice here is what we tell our own customers.